Loading...
Subscribe to Our Newsletter
Get the latest updates delivered straight to your inbox.
The ultimate L&D solution for upskilling your workforce.


© 2026 SkillUp MENA, Inc. All rights reserved
Subscribe to Our Newsletter
Get the latest updates delivered straight to your inbox.
The ultimate L&D solution for upskilling your workforce.
© 2026 SkillUp MENA, Inc. All rights reserved

 Share :


Anti Money Laundering Courses in Bahrain: Practising Escalation DecisionsA teller at a bank branch in Manama accepts a cash deposit from a regular customer, the third this week, each one just below the amount at which the bank’s own procedure calls for extra checks. She completed her annual AML training a month ago and passed its quiz with full marks. She hesitates, decides it is probably nothing, and serves the next customer. Weeks later, the pattern surfaces in a monitoring alert, and nobody can say whether she noticed it.
Her training taught her what money laundering is and listed the warning signs. It never asked her to make the decision she faced at the counter: is what I am seeing enough to raise an internal report, and how do I raise it without alarming the customer? Many anti-money laundering courses stop at awareness. The gap between recognising a red flag and deciding to escalate is where practice belongs.
This article is for HR teams and functional training owners in Bahraini financial institutions who want anti-money laundering courses to include practice in escalation decisions. It covers hypothetical scenarios written and reviewed with a compliance specialist, and a way to measure escalation quality without customer data. It is not a guide to choosing a programme; for that, see our article on comparing anti-money laundering course content by responsibility. Nor does it give legal or compliance advice: what must be escalated, and how, is defined by your compliance function and the requirements that apply to your institution.
Why Awareness in Anti-Money Laundering Courses Rarely Produces EscalationsEscalation is a judgement made under pressure. The employee sees only part of the picture: the customer may be familiar and pleasant, a queue is waiting, and there is a real fear of being wrong or of offending someone. A quiz on definitions does nothing to prepare people for that moment.
For conventional bank licensees, the Central Bank of Bahrain Rulebook, chapter FC-5 requires procedures to ensure that staff who handle customer business report promptly to the MLRO if they know or suspect money laundering or terrorist financing, or if a transaction or the customer’s conduct otherwise appears unusual or suspicious. Where staff consult their line managers first, that process must not be used to stop reports reaching the MLRO. Chapter FC-6 requires that relevant staff be made aware of the type of customer activity or transaction that may justify an internal STR and of the procedures for making one.
Being made aware is the starting point, and most anti-money laundering courses already cover it. Practising the decision is what makes it familiar enough to take at a busy counter. Other licensee categories should ask their compliance function which requirements apply to them.
What an Escalation Decision InvolvesBefore writing any scenario for your anti-money laundering courses, break the decision into parts that can be practised and scored. Your compliance function defines the right answer for each part under your own procedures:
Employees also hesitate because they fear consequences if a suspicion turns out to be unfounded. For conventional bank licensees, FC-5 now states that employees must not be held criminally, civilly, administratively or disciplinarily liable for reporting suspicions in good faith. Ask your compliance function to explain in the session how this applies in your institution; hearing it from them carries more weight than a slide.
Build Hypothetical Scenarios with a Compliance SpecialistEscalation practice in anti-money laundering courses stands or falls on its scenarios. The training owner drafts the structure; a compliance specialist, such as the MLRO, a deputy, or a compliance officer, supplies the typologies that matter for your products and approves every scenario and its model decision.
Build scenarios from typologies and invented details only. Never adapt real alerts or internal reports, even disguised: real reports are confidential, and a ‘disguised’ case may still be recognisable to staff who handled it. Names, amounts, dates and account details should all be fictional. The same principle of designing practice with synthetic records appears in our article on eLearning for financial services teams in Bahrain.
Write each scenario for one role’s actual work, whether the teller counter, the remittance desk, a relationship manager’s portfolio or a payments back office, and give it the same parts:
Mix the set deliberately: clear escalations, transactions that look unusual but have a documented explanation, and grey cases where the answer depends on one more fact. Include pressure, too: a long-standing customer, a senior client, or a colleague who suggests waiting until month end.
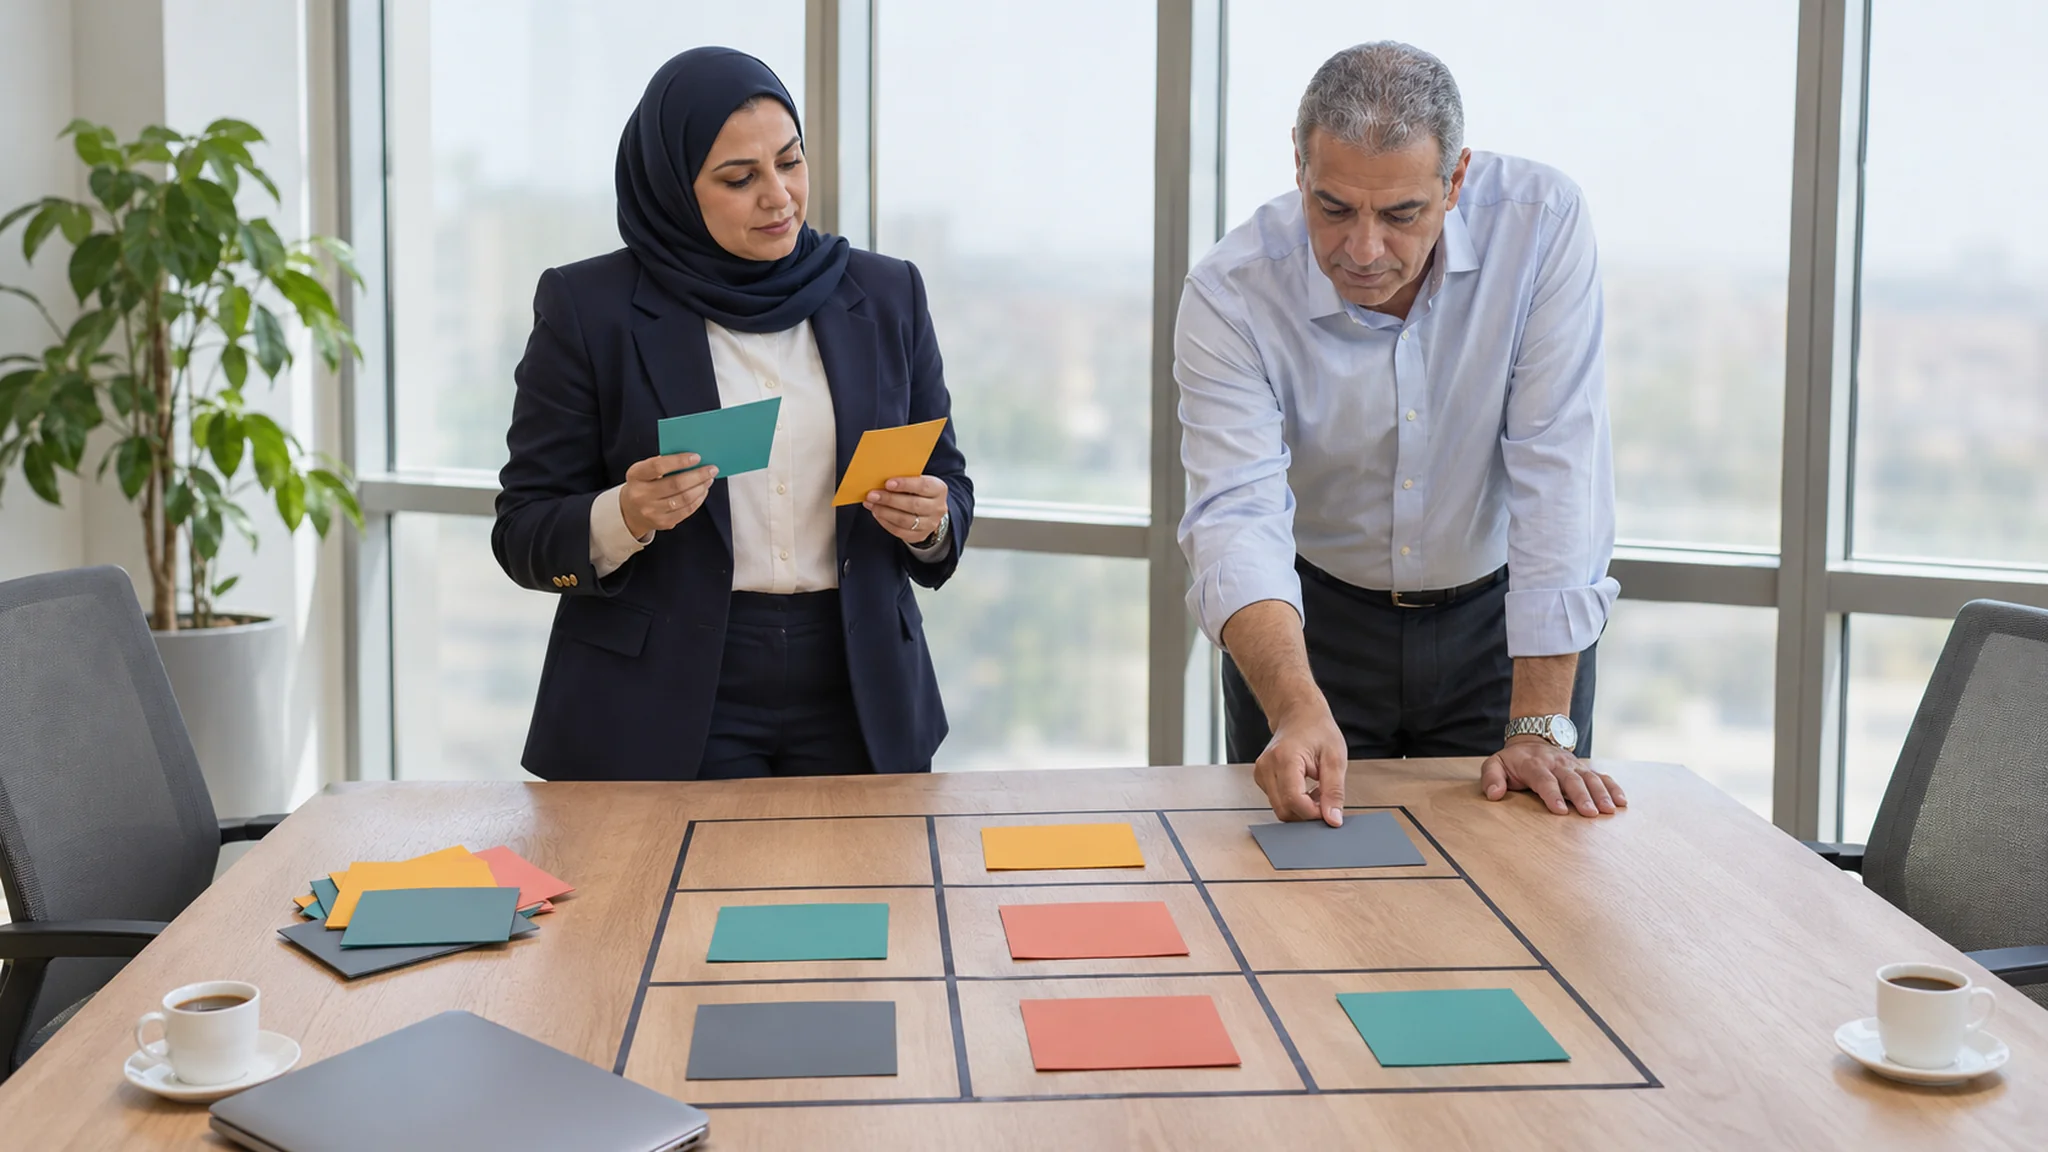
Run the Practice Inside Anti-Money Laundering CoursesShort, role-based sessions of 45 to 60 minutes work well, either as part of anti-money laundering courses or as a follow-up a few weeks later. Each round has three steps. First, every participant decides alone and writes the decision, three lines of reasoning, and a draft internal report. Second, the group compares answers without being told the model decision. Third, the compliance specialist explains the model decision, pointing to the deciding detail.
The quality of that feedback matters. In a widely cited review, Hattie and Timperley describe feedback as one of the most powerful influences on learning and achievement, while noting that its impact can be positive or negative. Feedback that names the detail the employee missed, and the fact they should have written down, teaches; feedback that labels a person as careless discourages the next report. Close each scenario with a two-minute role play in which the employee continues serving the customer normally, so that avoiding tipping off is practised, not just explained.
Measure Escalation Quality Without Customer DataBecause the scenarios are hypothetical, they can be scored openly. The compliance specialist scores each answer from 0 to 2 on five points:
Run a fresh scenario set before the practice in your anti-money laundering courses and again a few months later, and report averages by role rather than individual rankings. Do not treat the number of real internal reports as a training measure: it depends on many factors, and report content stays with compliance. If you deliver scenarios as eLearning, apply the review method in our guide to reviewing eLearning questions for decision quality in Bahrain so that each question tests the decision, not recall.
A Hypothetical Example: Escalation Practice at a Retail BankThis example is hypothetical and is included only to illustrate the method.
A conventional retail bank with branches in Manama, Muharraq and Riffa adds a 60-minute escalation session to its annual anti-money laundering courses for tellers and customer service staff. The training owner and a compliance officer write eight scenarios: three clear escalations, three unusual transactions with documented explanations, and two grey cases, including a long-standing customer whose deposits suddenly change pattern and a colleague who suggests waiting until month end.
In the first session, most participants handle the clear cases well, but few write internal reports the MLRO could act on; they describe the customer as ‘suspicious’ without saying what they saw. The compliance officer’s feedback focuses on facts and the deciding detail.
Three months later, a second scenario set shows stronger report content, while the ‘wait until month end’ case is still often delayed, so the next round of the bank’s anti-money laundering courses concentrates on it.
SummaryAnti-money laundering courses that stop at awareness leave employees alone with the hardest part: deciding whether to escalate. Practice built on hypothetical scenarios, with model decisions written and reviewed by a compliance specialist, makes that decision familiar before it happens at a real counter.
Score escalation quality on decision, timing, report content, channel and customer handling, using scenarios rather than customer data, and keep your compliance function in charge of what the right answer is. That turns anti-money laundering courses in Bahrain from a yearly reminder into practice that staff can use.
Click here. If you are planning anti-money laundering courses that include escalation practice for a specific role, you can discuss that requirement with the SkillUp MENA team.